Every property has a blind spot, and for most Portland rentals it's the part of the house nobody's ever billed rent for. The garage out back, the basement below the main floor, the attic with just enough headroom to stand in, these spaces sit quietly while the rest of the property carries the entire earning load, a gap that rarely shows up when owners work through measuring rental property performance.
Building a second unit on that same lot changes the equation. It puts existing square footage to work without requiring a new mortgage or a new address.
Key Takeaways
- A second unit generates rental income without the cost of purchasing another property.
- Oregon's streamlined permitting process has shortened the timeline for adding a unit in many Portland neighborhoods.
- A properly built second unit raises both monthly cash flow and long-term resale value.
- Financing structure, tax treatment, and upkeep costs shape the real return on a second unit.
- A local property management team helps owners avoid permitting delays and screening shortcuts.
What Separates a Real Unit From a Simple Addition
A finished bonus room or a converted den doesn't automatically qualify as a legal second unit under Oregon code. Three features separate a genuine unit from something that just looks like one:
- A private entrance, so tenants can come and go without walking through the main house
- A full kitchen, giving the space the ability to function on its own
- A private bathroom, so both households keep separate routines
Skip any one of these and the space can't legally operate as its own rental in most parts of Portland. Renters notice the gap fast, and city inspectors notice it faster.
Why Approval Timelines Have Shortened
Oregon cities have worked to simplify review for smaller accessory structures over recent years, and Portland has kept pace with that shift. Designs that once waited months for approval now move through review considerably faster, narrowing the distance between submitting plans and signing a lease. This mirrors a broader national trend, where 1 in 5 residential units approved in fast-growing states fall into this exact category.
Treat It Like Adding to Your Portfolio
Owners already comfortable with mastering portfolio management strategies tend to recognize a second unit as a similar kind of move, just applied to a property they already hold instead of a new acquisition.
An Attic That Became a Second Lease
One Portland owner we worked with had a walk-up attic above his garage that had functioned as nothing more than seasonal storage for over a decade. Holiday decorations, spare furniture, and boxes he meant to sort eventually filled the space, while his main house generated a single rent payment each month.
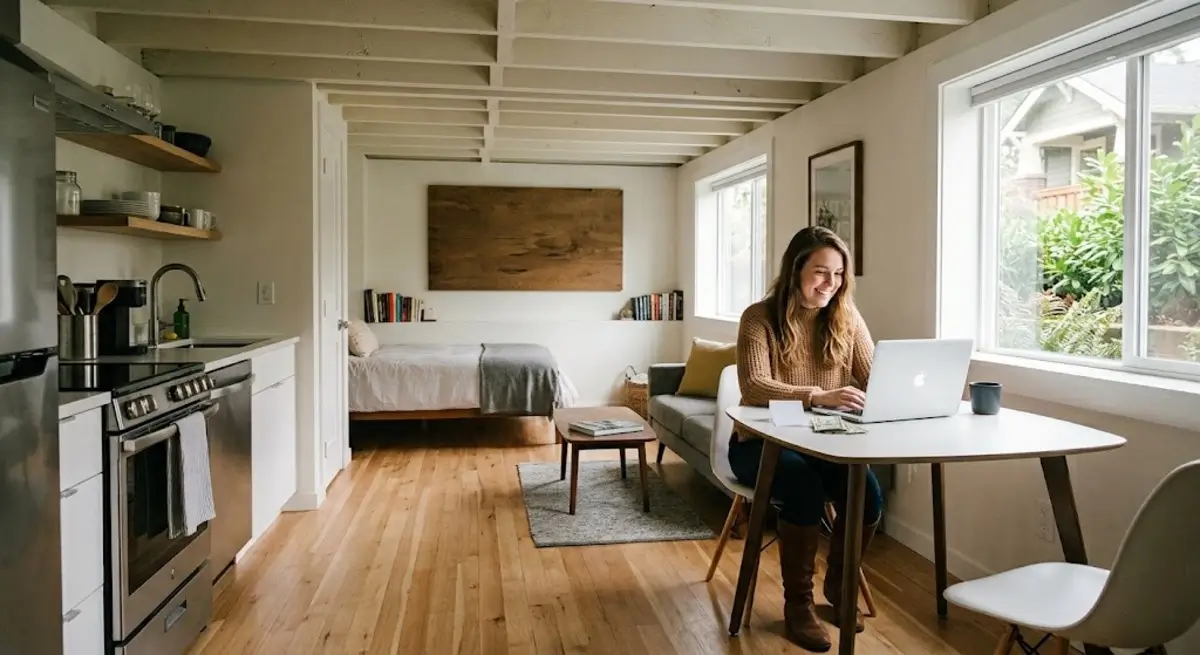
After finishing the attic with a kitchenette, a bathroom, and a private staircase entrance, he converted it into a compact studio. The property gained a second lease, his monthly income increased substantially, and buyers touring the home later noted the added unit as a meaningful selling point. His lot size stayed identical throughout the process. His willingness to treat unused square footage as an asset made the difference.
This pattern shows up in appraisal data too. Regulators studying California properties found the median appraised value for homes with an added unit reached $1,064,000 in 2023, a clear jump above comparable homes without one.
Where a Second Unit Performs Best Across Portland
Rental demand for a second unit varies considerably across different parts of Portland. A handful of location-based factors tend to drive most of that variation.
Location Factors Worth Weighing
- Distance from major employment centers and MAX transit lines, which shapes achievable rent
- Nearby schools, which attract steady interest from families seeking flexible housing for extended relatives
- Lot dimensions and setback requirements, which determine whether a garage conversion or a detached unit fits
A compact lot might only accommodate a garage conversion, while a larger lot could support a standalone structure with more separation between households. Owners weighing which upgrades pay off sometimes find a second unit delivers a stronger return than another round of cosmetic work on the main house.
Running the Numbers Before Construction Starts
Adding a second unit represents a significant financial decision, and owners need accurate projections rather than an inflated sales pitch. Before recommending this route for any property, we examine construction costs, achievable rent, financing terms, and payback timelines using comparable properties in the immediate area. An accessory unit functions as a capital improvement, fitting into a broader financial strategy rather than standing alone as a single purchase decision.
The Financial Details Owners Often Miss
Financing typically comes through home equity, a construction loan, or a cash-out refinance, with each option carrying distinct repayment terms worth comparing carefully.
- Home equity loans often carry lower rates but reduce equity available elsewhere
- Cash-out refinances can reset the terms of your primary mortgage
- Construction loans typically convert into a permanent mortgage once the build wraps up
Rental income from the unit counts as taxable income, requiring separate tracking of depreciation, insurance, and maintenance apart from the main home's records. Utility costs, landscaping adjustments, and ongoing repairs for the second structure need to factor into rent calculations from the outset. Owners looking for clarity on these numbers before moving forward can request a detailed rental income estimate drawn from comparable listings nearby.
Managing Two Units Means Managing Twice the Detail
A second unit brings a second lease, a second tenant relationship, and a second set of maintenance obligations. One owner we worked with, who converted his basement into a rental after his kids moved out, mentioned that keeping the two units' finances separate took longer to get comfortable with than the construction process itself.
Tenant screening still requires the same level of diligence, since a smaller unit doesn't warrant a lighter background check. Financial records need to stay separate as well, with income and expenses for the new unit tracked apart from the primary residence once tax documents come due. Owners overseeing two units on a single property often turn to structured monthly owner disbursements and reliable rent collection systems to keep everything organized from the very first month.
FAQs about ADUs in Portland, OR
Can I finance the construction using funds from my retirement account?
Some owners use a self-directed retirement account to fund construction, though this involves specific IRS rules and potential penalties if handled incorrectly. Speaking with a financial advisor before committing this route protects your retirement savings.
What happens if my lot already has a maxed-out lot coverage ratio?
If existing structures already use up allowable lot coverage, a detached unit may not be feasible, though interior conversions like basements or attics often still qualify. A quick zoning check clarifies which option applies to your lot.
Do I need to notify my mortgage lender before adding a second unit?
Many mortgage agreements require notifying the lender of significant property changes, especially if the work affects the home's structure or value. Checking your loan terms before construction begins avoids potential violations of your agreement.
Will the second unit need its own separate address for mail delivery?
Some jurisdictions assign a distinct address or unit number for mail and emergency services, while others allow a shared address with a unit designation. Local postal and fire department guidelines determine which applies to your property.
How soon can I list the unit for rent after receiving final approval?
Once final inspection and occupancy approval come through, the unit can typically be listed immediately. Many owners begin marketing the space a few weeks ahead of completion to reduce vacancy time after the certificate is issued.
Property That Works Twice as Hard
Most Portland owners never run the numbers on space they're not renting out, so the actual income potential stays a guess instead of a plan. PMI Bridgetown works through construction costs, permitting timelines, and realistic rent projections for your specific property, turning that guess into something you can act on. Get a custom estimate and see where the numbers land for your home.
